✦ AI Summary
Table of Content
▲
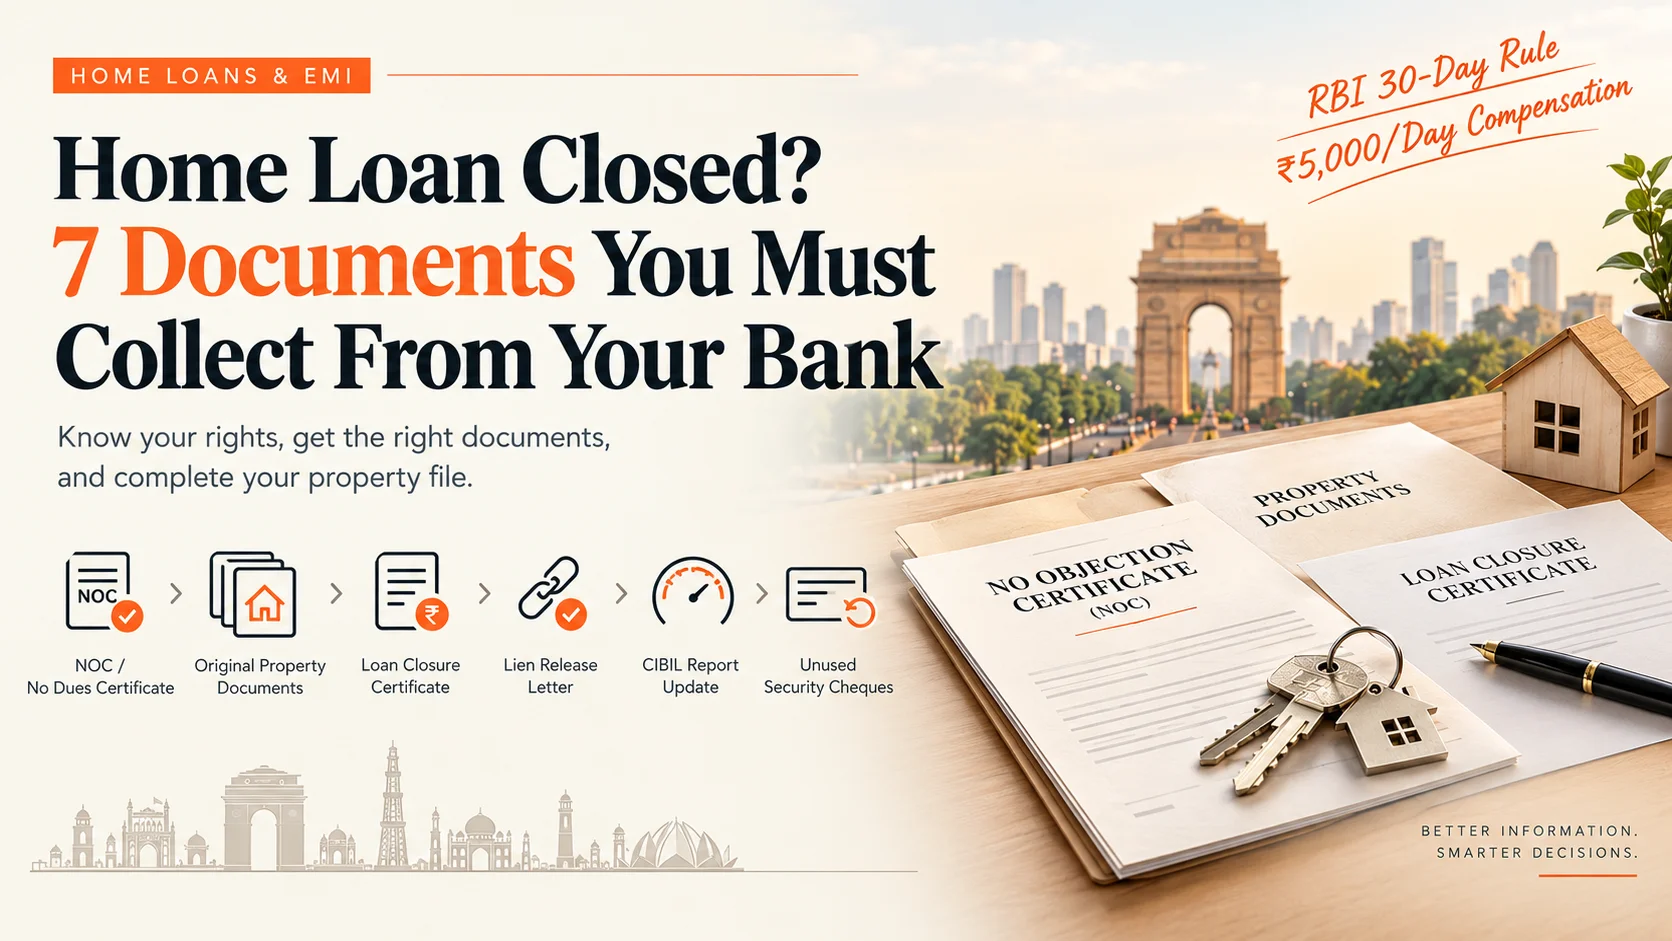
Yes, your bank owes you more than just a thank-you message once your home loan is fully repaid and they're legally required to hand it over within a specific window. Under RBI guidelines, lenders must return all original property documents and remove any charges registered against the property within 30 days of full repayment. If this hasn't happened within that window, you have a legitimate, enforceable grievance, not just an inconvenience.
The 30-Day Rule You're Entitled To
Yes, this is a concrete, current regulatory requirement. The Reserve Bank of India's guidelines, updated and in full force through 2026, state that lenders must return all original property documents and release related charges or liens within 30 days of full loan repayment or settlement. This applies whether your loan closed through regular EMI completion or through prepayment. If your bank is delaying beyond this window without a clear, specific reason, you're entitled to escalate through the bank's grievance process and, if unresolved, the Banking Ombudsman.
The 7 Documents
Yes, here's exactly what to collect, cross-referenced across multiple lenders' own stated processes:
- No Objection Certificate (NOC) / No Dues Certificate (NDC). This is the lender's formal written confirmation that your loan is fully repaid and they have no further financial claim on you or the property, the single most important document for any future sale, transfer, or fresh borrowing against the property.
- Original property documents. This includes your title deed or sale deed, allotment letter, possession letter, and any other chain-of-title documents the lender held as security throughout your loan tenure. Check every page against your own records, missing pages or an incomplete set is a common, easily-missed problem at this stage. If you are unsure which records should form part of your property file, see our guide to documents required to buy a property in India.
- Loan closure certificate / statement. A formal record confirming a zero outstanding balance and the account's closed status, distinct from the NOC itself.
- Lien release letter. A specific document confirming the bank's charge or lien over the property has been formally released, separate from the general NOC.
- MODT cancellation confirmation (where applicable). If your lender used a Memorandum of Deposit of Title Deed as the security instrument, confirm this has been formally cancelled, since it's a distinct registered instrument from the general lien.
- Updated CIBIL report. Confirm your credit report reflects the loan as genuinely "Closed," not merely "Settled" or still showing an open account; this affects your future borrowing eligibility and is worth checking directly rather than assuming it updates automatically.You can also understand how CIBIL score is calculated for a home loan before applying for your next loan.
- Unused security cheques. Any post-dated or security cheques you provided at the start of the loan should be returned or confirmed destroyed, since an unused cheque still in the bank's possession is an unnecessary lingering risk.
The Step Most Borrowers Miss Even After Getting the NOC
Yes, this is a genuinely important, often-missed point: getting your NOC does not automatically clear the CERSAI registry entry. CERSAI (the Central Registry of Securitisation Asset Reconstruction and Security Interest of India) maintains a separate, digital record of the charge or mortgage against your property, and this record does not update automatically just because your loan has closed and you've received your NOC. If this CERSAI charge isn't formally cleared, a future buyer's lender will still see it as an active charge during their own due diligence, something we've covered in detail in our property title verification checklist, creating real delays at resale time even though your loan itself has genuinely been paid off years earlier. Confirm directly with your lender that the CERSAI charge has been specifically removed, not just assume it's bundled into the NOC process.
Once that's confirmed, the final recommended step is to visit the Sub-Registrar's office and obtain an updated Encumbrance Certificate, confirming the registered mortgage entry has actually been reflected as released in the official land records, not just in the bank's own internal paperwork.
If the Bank Delays or Loses Your Papers
Yes, this genuinely happens, and there's a clear path forward. If your bank delays beyond the 30-day window, escalate first through the bank's internal grievance redressal officer, then to the Banking Ombudsman if unresolved. If the bank has lost your original property documents entirely, which does occur occasionally, the lender is obligated to assist you in reconstructing the title chain, typically through certified copies from the Sub-Registrar's office, and in some cases bears responsibility for costs incurred in this process a conversation worth having formally in writing with the bank rather than left to an informal assurance over the phone.

Ans 1. 30 days from the date of full repayment, under current RBI guidelines. If this deadline is missed without clear justification, you can escalate through the bank's grievance process and the Banking Ombudsman.
Ans 2. Not entirely. The NOC confirms the loan is repaid, but the CERSAI registry entry for the mortgage charge doesn't update automatically; this needs separate confirmation from your lender.
Ans 3. The NOC/No Dues Certificate, original property documents, a loan closure certificate or statement, a lien release letter, MODT cancellation confirmation (if applicable), an updated CIBIL report, and any unused security cheques.
Ans 4. CERSAI is a central registry recording charges against property used as loan security. If this charge isn't specifically cleared after closure, a future buyer's bank will still see it as active, causing delays at resale even though your loan is fully repaid.
Ans 5. The lender is obligated to assist in reconstructing your title chain, typically through certified copies from the Sub-Registrar's office. Put the request in writing rather than relying on a verbal assurance.
Ans 6. Yes, obtaining an updated Encumbrance Certificate confirms the mortgage release is reflected in the official land records, not just in the bank's internal paperwork.
Ans 7. Escalate first through the bank's internal grievance redressal officer, and if unresolved, to the Banking Ombudsman this is a regulatory deadline you're entitled to enforce.