✦ AI Summary
Table of Content
▲
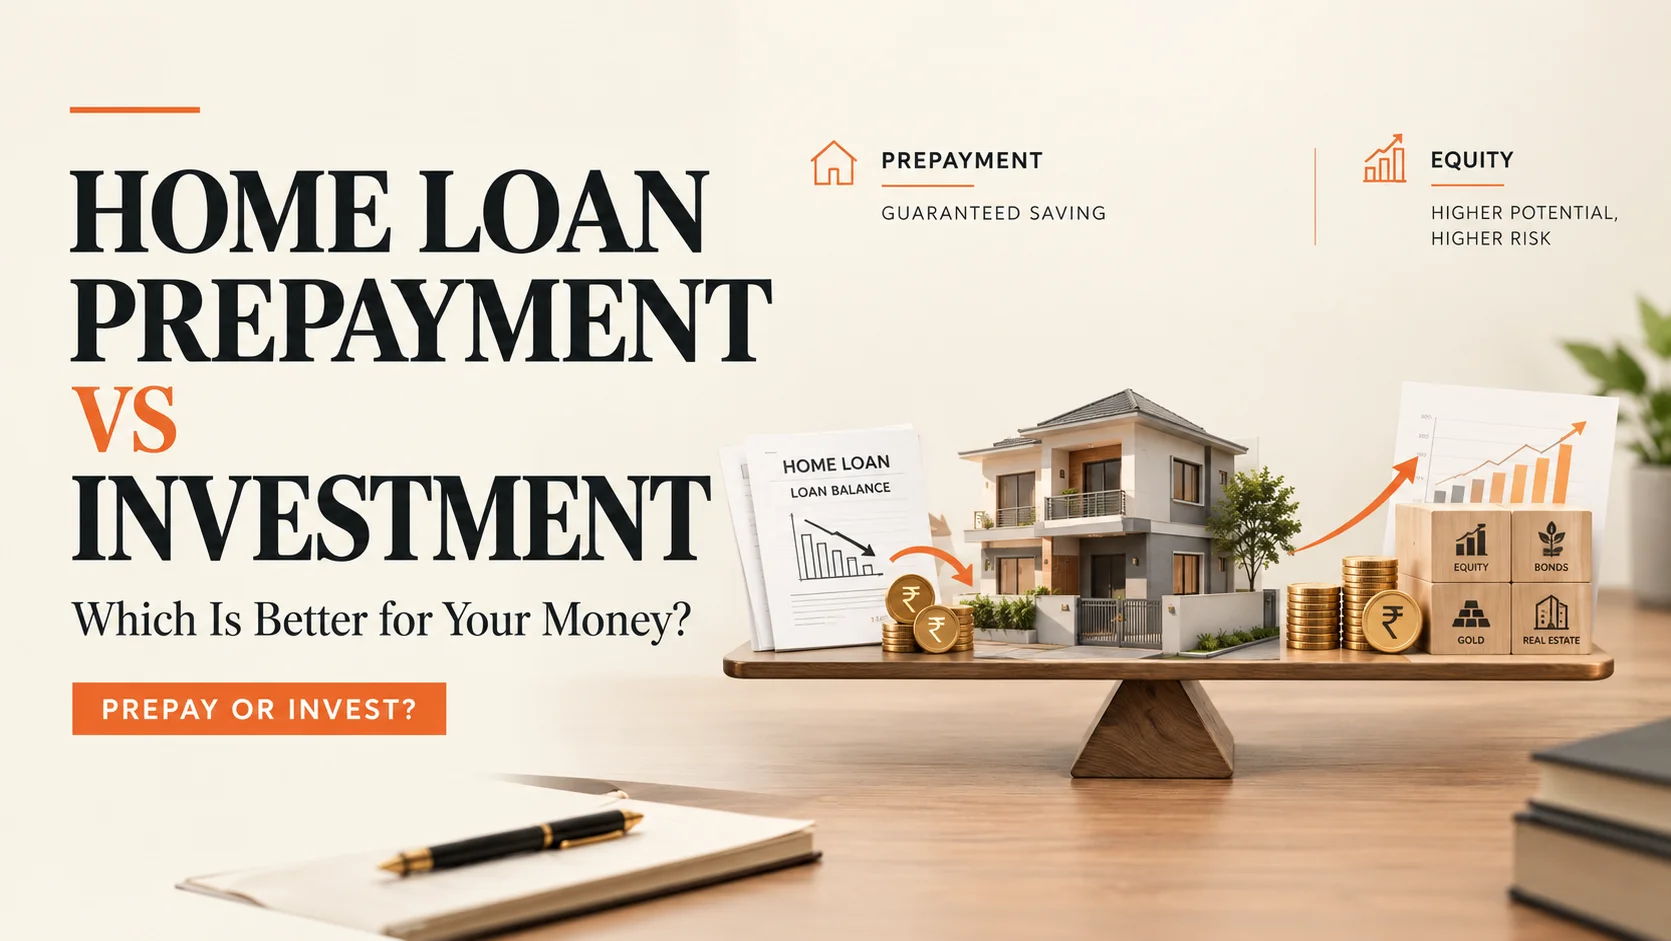
No, "investment" isn't really one single alternative to compare against prepayment and settling. That is the fastest way to make this decision. Prepayment essentially always beats parking your surplus in an FD, PPF, or debt fund once you account for tax, which means the real question isn't prepayment versus investment broadly. It's prepayment versus equity specifically.
The First Thing to Settle: Prepayment Beats FDs, PPF, and Debt Funds
Yes, almost without exception. Prepaying your home loan delivers a guaranteed, tax-free return exactly equal to your effective loan rate on current rates, that's commonly 7-9.5%. Compare that against what debt-type instruments actually deliver after tax: an FD paying 7-7.5% nets down to roughly 4.9-5.25% after tax for someone in the 30% bracket; a debt mutual fund taxed at slab rate lands similarly; even PPF, fully tax-free at 7.1%, sits below most current home loan rates. The conclusion across multiple independent financial analyses is consistent: the choice is never genuinely "prepay versus FD" prepaying wins that contest every time. The only investment category that can realistically outpace your loan rate after tax is equity, which is where the actual decision lives.
So the Real Question Is Prepay vs Equity Here's the Actual Bar
Yes, and the useful way to frame it isn't "will equity beat my loan rate on average," but "what specific pre-tax CAGR equity need to clear to justify investing instead of prepaying, given my actual loan rate and tenure." One recent, detailed worked example: at a 7.5% loan rate with 17.5 years remaining, equity needs to compound at roughly 8.2% pre-tax just to draw level with prepayment; a genuinely modest bar given equity's long-term historical average sits well above that. As your loan rate rises, that bar rises too: for a larger loan in the new tax regime, the breakeven climbs closer to 10% pre-tax, which is squarely within, rather than comfortably below, equity's typical long-term range.
As of late August 2026, the lowest home loan rates on offer in India sit around 7%, meaning the breakeven equity return for many current borrowers is genuinely achievable but not guaranteed equity remains volatile and taxed at 12.5% LTCG, while home loan tax benefits in India can also affect the effective cost of your loan. Prepayment's return, however, is certain and tax-free. . This is why the decision isn't purely mathematical: prepayment is a risk-free bet on a known number; equity is a probabilistic bet that typically clears that number over long horizons but carries real short-term uncertainty.
The Third Option Most People Don't Know About
Yes, there's a genuine hybrid structure worth knowing about: an overdraft-linked home loan (SBI MaxGain vs prepaying your home loan is a commonly cited comparison, and several other lenders offer comparable products) lets you park your surplus funds against the loan account itself. The parked amount reduces the interest calculated on your outstanding principal, exactly as a prepayment would, but the money remains fully liquid; you can withdraw it back out whenever you need it, unlike a genuine prepayment, which is gone from your hands once made. This is particularly useful if you're unsure whether to commit surplus permanently, or if your income is volatile enough that keeping access to the cash matters more than maximising the pure interest-saving effect of an irreversible prepayment.
The Order of Operations
Yes, there's a sensible sequence most credible sources agree on, regardless of where you land on the prepay-versus-equity question:
- Build an emergency fund first 6 to 12 months of expenses in a liquid fund or sweep-in FD, before a single rupee goes toward either prepayment or equity.
- Clear anything costing more than your home loan credit card debt (36-42%) and personal loans sit well above any home loan rate, and no investment realistically outpaces them.
- Decide the prepay-versus-equity split based on your effective loan rate, remaining tenure, and genuine comfort with investment discipline; the mathematical advantage of equity only materialises if you actually invest the surplus consistently, not if it quietly gets spent instead.
- Weight toward prepayment if you're within 5-7 years of retirement, carry income uncertainty (commission-based work, a startup, a less secure employer), or are simply more comfortable being debt-free sooner these are legitimate factors even when the pure math slightly favours investing.
Before making a large prepayment, it is also worth checking the hidden home loan charges that can affect the overall cost of borrowing.

Ans 1. Yes, almost always. Prepayment delivers a guaranteed, tax-free return equal to your loan rate, while an FD's after-tax return (roughly 4.9-5.25% for a 30% bracket taxpayer) typically falls below current home loan rates.
Ans 2. Generally yes. PPF's current 7.1% tax-free rate sits below most current home loan rates, meaning prepayment still wins this specific comparison for most borrowers.
Ans 3. It depends on your loan rate and tenure. One worked example shows equity needing roughly 8.2% pre-tax CAGR to break even against a 7.5% loan rate, rising toward 10% for larger loans in the new tax regime.
Ans 4. Yes, an overdraft-linked home loan (such as SBI's Max Gain) lets you park surplus funds against the loan to reduce effective interest while keeping the money withdrawable, unlike an irreversible prepayment.
Ans 5. Build a 6-12 month emergency fund first, then clear any debt costing more than your home loan (credit cards, personal loans), before allocating the remainder toward prepayment or equity.
Ans 6. As of late August 2026, the lowest rates on offer sit around 7%, though actual rates vary by lender, loan amount, and borrower profile.
Ans 7. Not necessarily. Proximity to retirement, income volatility, and personal comfort with debt are legitimate factors that can justify leaning toward prepayment even when equity's expected return slightly exceeds the breakeven bar.