✦ AI Summary
Table of Content
▲
Yes, hidden costs on a home loan can genuinely add several lakhs on top of your EMI over the loan's life but the single most valuable fact in this topic isn't a fee at all, it's a protection most borrowers don't know they already have: prepayment and foreclosure penalties are not legally permitted on floating-rate home loans in India.
The One Charge the Bank Legally Can't Impose (If Your Loan Is Floating Rate)
Yes, if your home loan is on a floating interest rate, which the vast majority of home loans in India are today, RBI and National Housing Bank directives prohibit lenders from charging a prepayment or foreclosure penalty, whether you're paying off the loan with your own funds or refinancing it through another lender. The "0-4% foreclosure charge" figure you'll see quoted across many sources genuinely only applies to fixed-rate loans, a much smaller share of the market. If you have a floating-rate loan and a lender tries to charge you for prepaying it, that's worth challenging directly, since it isn't a legally permitted charge. This connects directly to our guide on home loan prepayment vs SIP, particularly when borrowers are deciding what to do with surplus cash.
The Processing Fee Comparison Trap
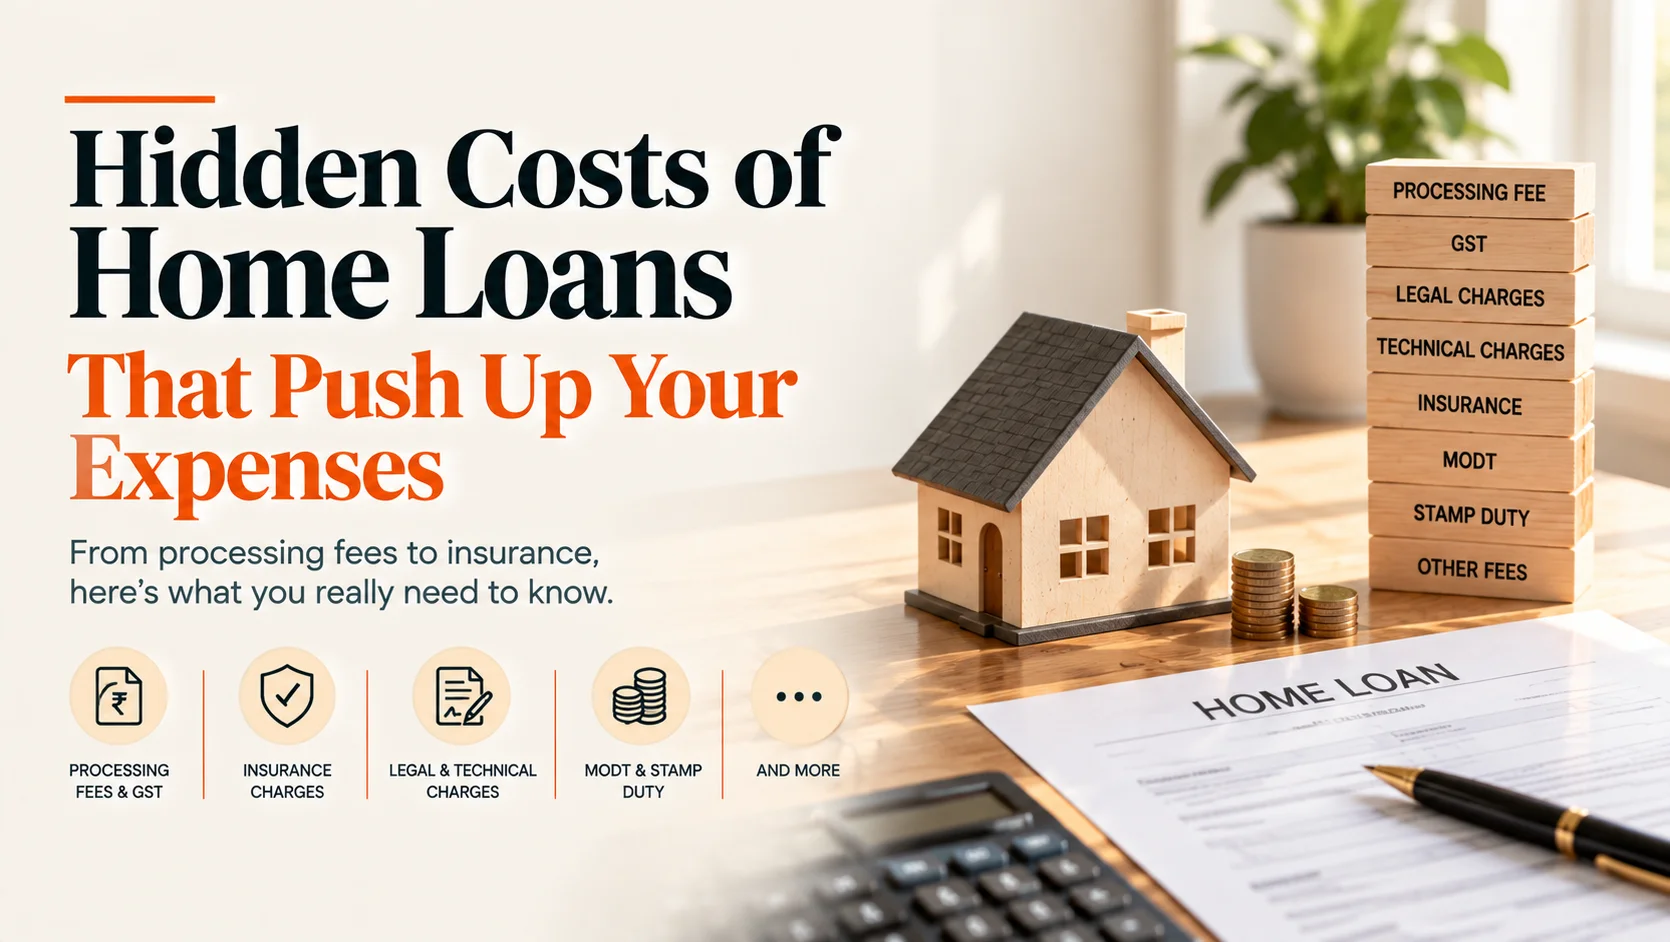
Yes the processing fee itself typically runs 0.25% to 2% of your loan amount, non-refundable even if your application is rejected, but the comparison trap is what happens next: 18% GST applies on top of the processing fee, as well as on legal, technical, and administrative charges. A ₹30,000 processing-plus-legal fee becomes ₹35,400 once GST is added. If you're comparing two lenders' quoted processing fees without accounting for this, you're comparing the wrong numbers and always ask for the GST-inclusive figure before judging which lender's fee is actually lower.
Legal, Technical, and Documentation Charges
Yes, expect ₹5,000-20,000 for legal verification and ₹2,000-10,000 for technical/valuation assessment, covering the lender's check of the property's ownership documents and construction quality. Beyond this, two often-missed documentation costs apply: MODT (Memorandum of Deposit of Title Deed) charges, typically 0.1-0.2% of the loan amount, and a separate stamp duty on the loan agreement itself, distinct from the stamp duty you pay on the property's registration, commonly around 0.2% of the loan amount plus a Notice of Intimation fee of roughly ₹1,000 in states where this applies. It's easy to assume you've already accounted for "stamp duty" once you've budgeted for the property's registration cost; this loan-document stamp duty is a genuinely separate line item.
If MODT is unfamiliar, our guide on how MODT works in home loans explains how the mortgage is created, when the title deeds are deposited and why the charges vary by state.
Insurance: What's Mandatory vs What's Being Sold to You
No, not all loan-related insurance is actually mandatory, and knowing the difference can save you a meaningful sum. According to BankBazaar CEO Adhil Shetty, "property insurance is usually mandatory; loan protection insurance is optional," and he specifically notes that disputes commonly arise when lenders bundle a single-premium loan protection policy into the loan amount without clear borrower consent. Property insurance protects the physical asset and is a reasonable requirement given it's the bank's collateral. Loan protection (credit life) insurance, which pays off the loan if something happens to you, is a separate, optional product you're free to decline it, buy a cheaper independent term plan instead, or shop around for competitive quotes rather than accepting whatever the lender bundles in at loan signing.
Some home-loan costs and interest payments also have tax implications, so borrowers should understand the available home loan tax benefits in India separately from the upfront charges discussed here.
The Smaller Charges That Add Up
Yes, several smaller fees genuinely add up over a loan's life: EMI bounce charges of ₹500-1,500 per missed instance, a CERSAI registration fee (a small, mandatory charge supporting the central security interest registry), and a conversion or rate-switch fee of roughly 0.25-1% of the outstanding amount if you later switch between interest rate benchmarks or negotiate a lower rate with your existing lender. None of these individually is large, but across a 15-20 year loan tenure, they're worth factoring into your total cost comparison between lenders rather than treating the headline interest rate as the only number that matters.

Ans 1. No, not if your loan is on a floating interest rate. RBI and NHB regulations prohibit prepayment and foreclosure penalties on floating-rate home loans. This protection does not apply to fixed-rate loans.
Ans 2. Yes, 18% GST applies on the processing fee as well as legal, technical, and administrative charges, meaningfully increasing the quoted fee once you account for it.
Ans 3. Property insurance is typically mandatory, protecting the asset serving as collateral. Loan protection (credit life) insurance is generally optional, and lenders bundling it into your loan without clear consent is a known source of borrower disputes.
Ans 4. Yes, the Memorandum of Deposit of Title Deed is a distinct charge, typically 0.1-0.2% of the loan amount, separate from legal and processing fees.
Ans 5. Yes many states levy a separate stamp duty on the loan document itself, commonly around 0.2% of the loan amount plus a Notice of Intimation fee, distinct from the stamp duty paid on the property's own registration.
Ans 6. Processing fees and administrative charges are the most commonly negotiable, especially with a strong credit profile or a higher down payment. Legal, technical, and statutory charges like MODT and stamp duty are generally fixed and non-negotiable.
Ans 7. Processing fee structures genuinely vary by lender; some charge a percentage, others a flat fee with a cap, and some waive it entirely as a promotional offer making it worth comparing the actual rupee figure, GST included, rather than the headline percentage alone.