✦ AI Summary
Table of Content
▲
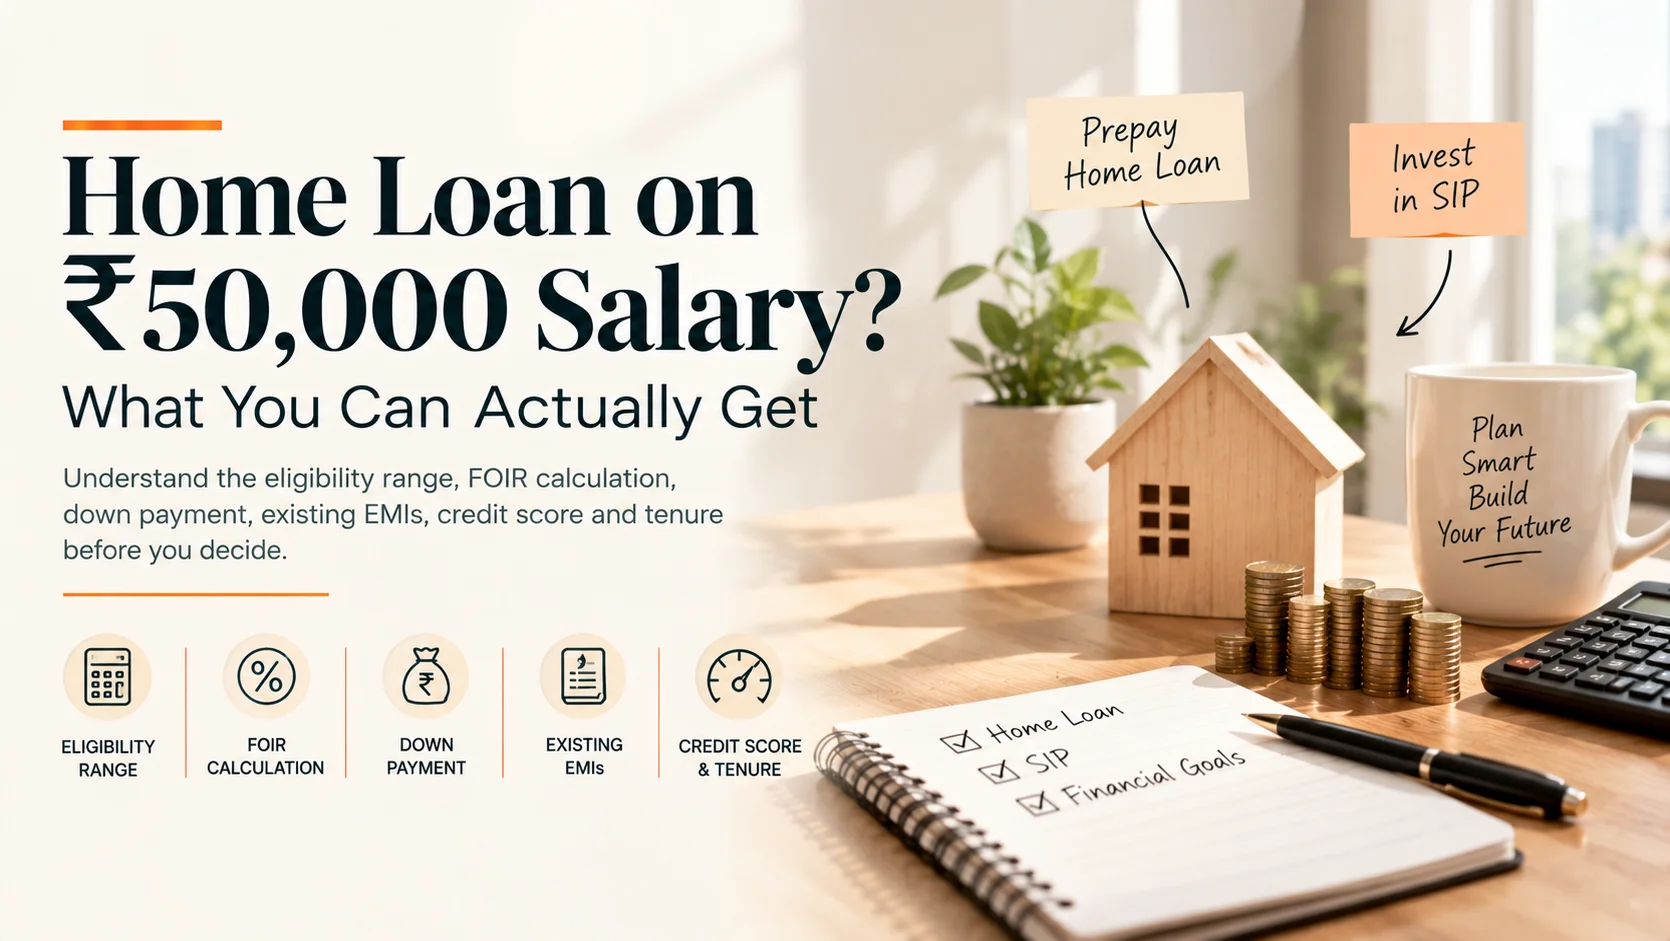
Yes a ₹50,000 monthly salary comfortably qualifies for a home loan in most Indian cities. The honest range, though, isn't one precise number. Different lenders apply genuinely different eligibility policies to the same salary, which is why you'll see figures anywhere from roughly ₹23 lakh to over ₹32 lakh quoted for this exact income, with no single one of them being "wrong."
The Direct Answer
For a salaried applicant earning ₹50,000 a month take-home, with no existing loan EMIs and a credit score above 700, most lenders' calculators land in the ₹23-32 lakh range for a 20-year loan at current rates. The spread exists because banks apply different FOIR (Fixed Obligation to Income Ratio) caps to the same income bracket, some cap it at 40%, others go as high as 55% for this salary level and use slightly different reference interest rates (typically 8.35-9.5% currently). Getting quotes from two or three lenders, rather than trusting a single online calculator, is the only way to know your actual number rather than an estimate.
How the Number Is Actually Calculated
Every lender uses the same underlying formula, even though the specific inputs vary: Available EMI = (Net Monthly Salary × FOIR cap) − Existing EMIs. That available EMI is then converted into a loan amount using the interest rate and tenure on offer.
On ₹50,000, using a 40% FOIR (the more conservative end applied by some lenders to this income bracket) gives an available EMI of ₹20,000, translating to roughly ₹23 lakh at 8.5% over 20 years. Using a 50% FOIR (applied by other lenders for this same salary) gives ₹25,000 available EMI, translating to roughly ₹28-30 lakh the range most commonly cited as the benchmark for this exact salary and credit profile.
Lenders use different approaches to assess affordability, so understanding how lenders calculate home loan eligibility can help explain why two borrowers with the same salary may receive different loan amounts.
Any existing EMI reduces this directly, rupee for rupee. If you're already paying ₹10,000 a month toward a car loan, that comes straight off your available EMI capacity before the home loan calculation even starts a ₹10,000 existing EMI can reduce your eligible home loan by roughly ₹11-12 lakh, a genuinely large swing for what might feel like a small monthly commitment.
The Second Ceiling Nobody Mentions Enough Your Down Payment
FOIR tells you the maximum EMI you can service but it isn't the only limit. Banks also cap financing at 80% of the property's value or registered price, whichever is lower, meaning you need at least 20% of the property price as a cash down payment, regardless of how much EMI you could technically afford.
This matters practically: someone eligible for ₹28 lakh by FOIR calculation still needs roughly ₹7 lakh in cash if buying a ₹35 lakh flat. For many first-time buyers at this income level, arranging the down payment, not the EMI eligibility itself, ends up being the harder practical constraint worth planning for as seriously as the loan eligibility number itself.
What Actually Moves This Number
A few factors genuinely change your eligible amount, in roughly this order of impact:
Clearing existing EMIs before applying. As shown above, removing a ₹10,000 monthly obligation can add back over ₹10 lakh in eligibility the single biggest lever most applicants overlook.
Adding an earning co-applicant. If your spouse or a parent also earns ₹50,000 a month, the FOIR calculation applies to the combined ₹1,00,000 income, substantially expanding available EMI capacity, a decision covered in more depth in our joint home loan guide.
Before applying, it is also useful to understand how lenders evaluate your CIBIL score for a home loan, since your credit history is one part of the overall credit assessment. Your credit score. A score above 750 generally secures a better interest rate than a borderline score, which itself increases the loan amount the same EMI capacity can support.
Tenure, within your age limit. Loan tenure is capped so the loan finishes by age 65 (70 for government employees) a 35-year-old can typically get a 30-year tenure, while a 50-year-old is limited to around 15 years, which meaningfully reduces the maximum loan amount for an older applicant at the same salary, since a shorter tenure means a higher EMI for the same loan amount.
Employer type. Government and MNC employees generally receive a higher income multiplier from banks than applicants from less-established employers, given the perceived income stability.
_1788769952.webp)

Ans 1. Yes, most lenders offer a home loan in the ₹23-32 lakh range for a ₹50,000 monthly salary, over a 20-year tenure, assuming no existing EMIs and a good credit score.
Ans 2. Lenders apply different FOIR caps to the same income bracket some use 40%, others up to 55% and different reference interest rates, producing a genuine range rather than one universal figure.
Ans 3. Yes, significantly. Any existing EMI is subtracted from your available EMI capacity before the home loan is calculated. A ₹10,000 existing EMI can reduce eligibility by roughly ₹10-12 lakh.
Ans 4. Banks finance a maximum of 80% of the property's value, so you'll need at least 20% of the property price as a cash down payment, regardless of your EMI eligibility.
Ans 5. Yes if your co-applicant also has income, the FOIR calculation applies to your combined income, substantially expanding your available EMI capacity and loan eligibility.
Ans 6. Yes. Loan tenure is capped so the loan finishes by 65 (70 for government employees), meaning an older applicant gets a shorter tenure, a higher required EMI for the same loan amount, and therefore lower overall eligibility.
Ans 7. Clearing existing EMIs before applying typically has the biggest single impact, followed by adding an earning co-applicant and improving your credit score above 750.