✦ AI Summary
Table of Content
▲
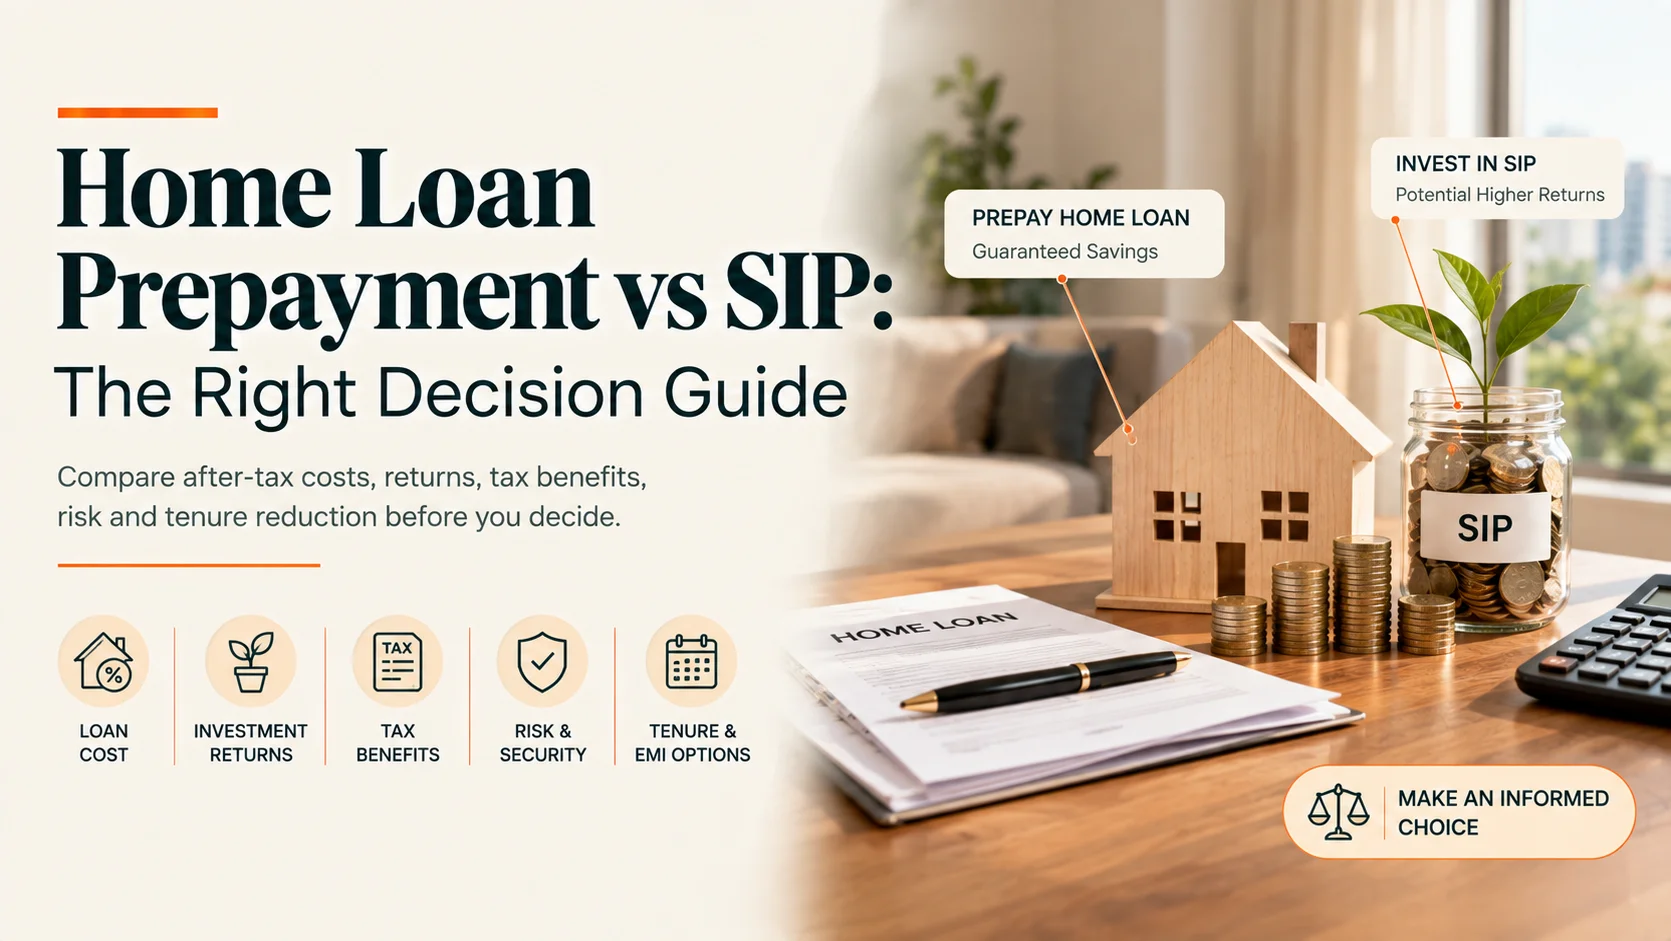
The comparison most people make "my SIP could return 12%, my loan only costs 9%, so I should invest" is comparing the wrong numbers. One figure is pre-tax and uncertain; the other needs a tax adjustment before it means anything. Getting this comparison right, and one specific choice about how you prepay if you go that route, can be worth lakhs over the life of a loan.
The Comparison Almost Everyone Gets Wrong
Your home loan's nominal interest rate isn't what it actually costs you if you're claiming a tax deduction on it. Your SIP's expected return isn't what you'll actually keep either, once long-term capital gains tax applies. The correct comparison is: your effective after-tax loan rate versus your expected after-tax investment return, not the two headline numbers side by side.
Calculate Your Effective Rate First
If you're in the old tax regime and claiming the Section 24(b) deduction (up to ₹2 lakh a year on interest for a self-occupied property), your effective rate is meaningfully lower than your stated rate. The calculation: effective rate = nominal rate × (1 − your tax bracket). On an 8.5% loan, someone in the 30% bracket gets: 8.5% × 0.70 = 5.95% effective.
If you're in the new tax regime, where this deduction isn't available (a distinction already covered in our joint home loan guide), your effective rate is simply your nominal rate no adjustment. This alone can shift the decision meaningfully, since a 8.5% loan in the new regime costs you the full 8.5%, not 5.95%.
For a broader explanation of how these deductions work, see our guide to home loan tax benefits in India 2026.
On the investment side, Nifty 50 has delivered roughly 12-13% CAGR over the last 20 years, but after the current 12.5% long-term capital gains tax on equity gains above ₹1.25 lakh a year, your realistic after-tax return sits closer to 10-11% a figure worth using instead of the headline pre-tax number.
The honest grey zone, based on multiple sources' frameworks: if your effective loan rate sits below roughly 8%, investing the surplus tends to win mathematically. Above roughly 9-9.5%, prepayment's guaranteed saving tends to be the stronger choice. Between those two figures, it's genuinely close enough that other factors covered below should decide it.
If You Do Prepay This One Choice Matters More Than the Amount
This is the single most underused, high-value detail in this entire decision, and most simpler comparisons skip it entirely. When you make a prepayment, your lender typically offers two options: reduce your EMI (keep the same tenure, pay less each month) or reduce your tenure (keep the same EMI, finish the loan sooner). These are not equivalent, even for the identical prepayment amount.If you're considering a more flexible way to reduce home-loan interest without permanently locking away your cash, you can also compare this with SBI MaxGain vs prepaying your home loan.
A concrete illustration: on a ₹5 lakh prepayment, choosing EMI reduction might save roughly ₹6 lakh in total interest over the loan's remaining life, while choosing tenure reduction on the exact same amount can save closer to ₹10 lakh nearly double, for no additional cost to you. Always choose tenure reduction over EMI reduction when prepaying, unless your monthly cash flow genuinely requires the lower EMI to stay comfortable.
The Risk You're Not Comparing
This deserves to be stated plainly rather than glossed over: prepayment savings are guaranteed; SIP returns are not. If you prepay ₹1 lakh on an 8.5% loan, you save exactly 8.5% on that amount going forward, with zero risk. A SIP's 12-13% historical average requires staying invested through multiple market cycles, including years where equity markets deliver flat or negative returns, without panic-selling along the way. Presenting both figures side by side as if they carry equal certainty is the single biggest flaw in most casual comparisons of this decision; a 12% assumption and an 8.5% guarantee are not the same kind of number.
If your loan is jointly held, the tax calculation can be different depending on ownership, repayment contribution and tax regime; our joint home loan guide explains these distinctions in detail.
The Honest Answer
There is no single correct answer, and every credible source on this topic says so directly. What the math and behavioural evidence together suggest:
- If your effective loan rate is comfortably below 8%, and you have a long investment horizon (10-15+ years) and genuine risk tolerance, investing the surplus is the mathematically stronger path.
- If your effective loan rate is above 9-9.5%, especially in the new tax regime with no 24(b) benefit, prepayment's guaranteed saving is the stronger, lower-risk choice.
- Before committing to either, make sure you have an adequate emergency fund both prepayment and SIP investing lose to having no cushion for a genuine emergency.
- If job security, income volatility, or approaching retirement weigh on you, shift toward prepayment even if the math slightly favours investing, the psychological value of reduced debt is real, and several advisers explicitly weigh this alongside the pure numbers.
- Many financially disciplined borrowers do both a partial prepayment (via tenure reduction) alongside a smaller, consistent SIP rather than committing the entire surplus to one path.
_1788769952.webp)

Ans 1. Your after-tax (effective) rate. If you're in the old tax regime claiming Section 24(b), your effective rate is your nominal rate reduced by your tax bracket. In the new regime, with no 24(b) benefit, your effective rate equals your nominal rate.
Ans 2. Tenure reduction, significantly. On the same prepayment amount, choosing tenure reduction over EMI reduction can nearly double your total interest saved over the loan's remaining life.
Ans 3. Use an after-tax figure, not the headline pre-tax number. Nifty 50 has returned roughly 12-13% CAGR over 20 years pre-tax; after current LTCG tax, a realistic after-tax figure is closer to 10-11%.
Ans 4. Yes, in a specific sense worth understanding clearly: prepayment savings are guaranteed the moment you make them, while SIP returns depend on market performance and require staying invested through down cycles without panic-selling.
Ans 5. Roughly 8-9.5% effective rate, based on multiple financial frameworks below this range, investing tends to win mathematically; above it, prepayment's guaranteed saving tends to be stronger. Within the range, other factors should decide.
Ans 6. Many financially disciplined borrowers do exactly this a partial prepayment via tenure reduction alongside a smaller ongoing SIP rather than committing all surplus to a single path.
Ans 7. Confirm you have an adequate emergency fund first both prepayment and SIP investing are secondary to having a genuine cash cushion for unexpected expenses.